Computing Infrastructure and Technological Capability Are Becoming Matters of National Strategy
A person in Kampala can open an application and ask an artificial intelligence system to explain a difficult subject, translate a passage or help prepare a document. The response may appear almost immediately, with little to suggest that its production depends upon industrial facilities scattered across several countries.
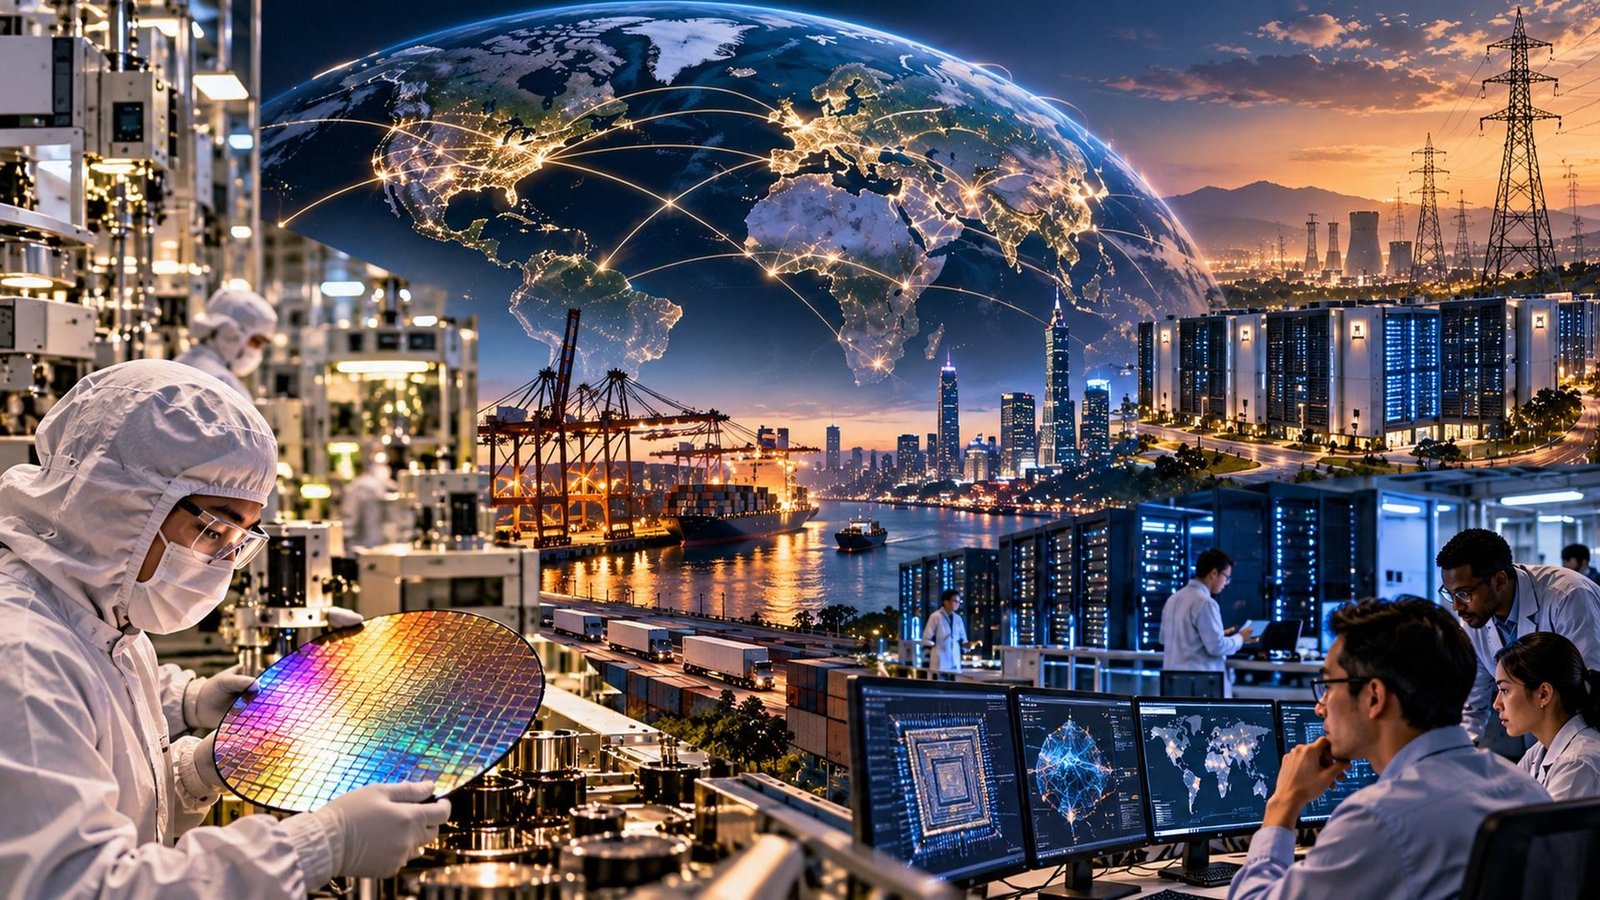
The processor performing the calculation may have been designed in the United States and manufactured in Taiwan, using highly specialised equipment from the Netherlands. Some of its memory components may come from South Korea. The computer may be operating inside a data centre hundreds or thousands of kilometres from the person asking the question, drawing electricity from an entirely different national power system.
The apparent simplicity of artificial intelligence conceals an unusually international industry. Its most valuable products are delivered through software, but the machinery that makes them possible is physical, expensive and difficult to manufacture. This is becoming increasingly important to governments as well as technology companies.
For much of the past two centuries, countries gained industrial influence by developing productive capacity in steel, machinery, electricity, transport and manufacturing. Computing later became central to economic and military organisation, communication and scientific research.
Artificial intelligence is adding another dimension to that familiar relationship between technology and national power.
Countries want access to advanced computing not only because it may produce profitable businesses, but also because it can support research, public services and industries upon which their economies depend. Some are investing in domestic infrastructure, others are building partnerships, and many are considering how much reliance upon foreign technology they can comfortably accept.
The competition is real, although it is more complicated than a contest between two countries. The same international connections that create dependence also make progress possible. No single nation controls every essential part of the modern AI industry, and success in one area does not necessarily translate into leadership everywhere else.
Industrial Power Has Always Had a Geography
The First Industrial Revolution began in Britain under circumstances that made large-scale mechanisation commercially possible. Coal, expanding transport networks, investment and manufacturing expertise helped establish factories capable of producing goods in quantities that traditional workshops could seldom match. British industrial development eventually influenced trade, finance and political power far beyond the country’s borders.
The Second Industrial Revolution changed that balance. Germany and the United States became leading centres of heavy industry, chemicals, electrical technology and large-scale manufacturing. Their influence depended not only on individual inventions but on the ability to build productive systems around them, supported by skilled workers, research institutions, financial resources and infrastructure.
The Third Industrial Revolution brought a further shift. American companies played a major role in semiconductors, personal computing and software, while Japanese and other Asian manufacturers became central to electronics production. Over time, semiconductor manufacturing and the assembly of digital equipment developed into intricate international supply chains. A computer might be conceived in one country, assembled in another and sold almost everywhere.
These developments are a reminder that technological leadership is rarely permanent or confined to a single invention. It develops through an industrial ecosystem and can change when other countries acquire the skills, institutions and capital needed to compete.
Artificial intelligence is now strengthening the strategic importance of that ecosystem. A country may produce outstanding researchers but lack the computing facilities needed to develop the largest models. Another may possess abundant energy and investment capital without yet having a comparable pool of technical expertise. A third may manufacture indispensable equipment while producing relatively few AI applications for consumers.
The distribution of these capabilities helps explain why governments are taking a closer interest in the geography of the industry. They are not simply asking which country has produced the most impressive chatbot. They are asking whether their businesses and researchers will have dependable access to the technologies likely to shape future economic activity.
The Most Advanced Chips Depend on a Global Supply Chain
A useful place to begin is the semiconductor. Advanced AI systems require processors capable of carrying out enormous numbers of mathematical operations, often simultaneously. Their development has created exceptional demand for powerful computing hardware, but the process of making that hardware depends on expertise spread across several countries.
American companies such as Nvidia are prominent in designing AI processors. Designing a processor, however, is different from manufacturing one. Some of the world’s most sophisticated chips are produced by Taiwan Semiconductor Manufacturing Company, commonly known as TSMC, which operates facilities capable of manufacturing the extremely small and complex components used in leading computing systems.
Those factories depend in turn upon specialist equipment. ASML, based in the Netherlands, is the world’s only manufacturer of the extreme-ultraviolet lithography machines used for critical stages of the most advanced chip production. The machinery works with extraordinary precision to create tiny patterns on silicon wafers. Its existence reflects decades of research and a supply network of specialised businesses rather than the achievement of one company working alone.
South Korean manufacturers are important suppliers of advanced memory, while Japanese, European, American and other firms contribute materials, chemicals, testing equipment and components. The completed processor is therefore the outcome of a production chain that crosses national borders many times before it reaches a data centre.
Stanford University’s 2026 AI Index reports that TSMC manufactures almost all leading AI chips, illustrating the degree to which advanced computing depends on manufacturing capacity concentrated in Taiwan. This is an industrial strength, but also a potential vulnerability if disruption prevents manufacturers from supplying customers. The concern is not limited to political tensions; natural disasters, electricity failures and interruptions to trade can also affect complex production networks.
The importance of chips helps explain the policies that have emerged around their export. The United States has restricted access to certain advanced computing technologies in China, citing national-security concerns. These restrictions have evolved over time rather than operating as a complete prohibition on every AI processor. In January 2026, for example, the US Department of Commerce announced that applications to export specified processors, including Nvidia’s H200, could be reviewed individually subject to conditions.
China has meanwhile invested in domestic semiconductor capacity and AI development, seeking alternatives where foreign technology is difficult to obtain. It remains part of a broader international system of trade and research, but its efforts reveal why access to computing hardware has become a matter of national strategy.
The same pressures are encouraging the diversification of manufacturing. TSMC and other companies have been expanding production outside their established bases, although building a fabrication plant is expensive and establishing a fully competitive industrial ecosystem takes time. A new factory does not immediately reproduce every supplier, technician and production method that supports an existing manufacturing centre.
The United States and China Lead in Different Ways
Much discussion of artificial intelligence describes a race between the United States and China. There is a basis for the comparison: both countries have large research communities, major technology companies, significant investment and ambitions to lead in advanced computing. But even between these two countries, the measurements of leadership do not always point in the same direction.
The United States has exceptional strengths in commercial AI development, chip design, cloud computing and private investment. It hosts major model developers and technology companies whose products reach users throughout the world. Stanford’s 2026 AI Index estimated US private AI investment at approximately $286 billion in 2025, substantially above the corresponding private investment it recorded for China. The comparison needs qualification because privately reported investment does not capture the full scale of Chinese state-backed support.
China has considerable strengths of its own. It possesses a large industrial base, extensive digital markets and significant research activity, while its developers have produced increasingly competitive AI systems. The 2026 AI Index found that the performance gap between leading American and Chinese models had narrowed substantially, with the top systems trading the lead at different points during the preceding year.
The distinction matters because a country’s position cannot be summarised by the performance of a single model. Scientific publications, engineering talent, computing capacity, investment, patents, robotics and actual business adoption all provide different views of technological capability. China, for example, has a major presence in industrial robotics and scientific publications, while the United States remains particularly strong in frontier model development and private investment.
Competition between them is also influencing policy. The American government has used export controls to regulate transfers of certain technologies, while Chinese policy has encouraged domestic capabilities in strategically important industries. Each country wants to reduce vulnerabilities that could arise if essential technologies become unavailable during political or commercial disputes.
Yet the relationship is not one of complete separation. Technology companies sell into international markets; research ideas circulate across borders; and semiconductor manufacturing still relies on specialised suppliers in several countries. Attempts to reduce dependence may alter these connections, but duplicating them in full would be costly and time-consuming.
The more accurate picture is one of competition taking place within an industry that remains deeply interconnected. Governments may wish to secure greater independence, but the commercial advantages of international specialisation are difficult to abandon.
Other Countries Are Building Their Own Capabilities
The desire to become less dependent upon a small number of foreign suppliers extends well beyond Washington and Beijing. Across Europe, Asia and the Middle East, governments are trying to create conditions in which domestic researchers and businesses can obtain the computing resources they need.
The European Union has adopted an AI Continent Action Plan that combines investment in computing facilities with programmes supporting research and business adoption. Its network includes 19 AI Factories, established or being developed around European supercomputing facilities, with additional access points intended to serve researchers and smaller enterprises. In July 2026, the European Commission launched a call to develop large AI Gigafactories, envisaging substantial public and private investment. The projects should be understood as programmes at differing stages of development, not as facilities that are all already operating.
Europe’s approach reflects concerns about competitiveness and the practical ability to develop AI within its own legal and economic environment. Access to domestic computing can be valuable for scientific institutions, businesses handling sensitive information and developers who want alternatives to a limited number of foreign cloud platforms.
India is pursuing a somewhat different strategy. Its IndiaAI Mission is intended to broaden access to computing and support the development of models and services suited to Indian needs. Government figures published in 2026 reported more than 45,000 graphics processors available through the shared computing programme by June, with subsidised access for approved projects. The objective is not simply to produce one prominent model, but to give researchers and businesses opportunities to build and test useful systems without individually financing expensive infrastructure.
Other countries are investing according to their own circumstances. Saudi Arabia has established programmes to encourage AI-ready data centres, drawing upon energy resources, investment capital and a desire to diversify economic activity. The United Arab Emirates has likewise made AI and data central to its digital-government and economic development plans. These initiatives show how countries with different strengths may attempt to enter the industry through infrastructure, partnerships or specialised applications.
Not every national project will succeed. Large computing facilities require paying customers, skilled operators, dependable electricity and continuing investment as equipment changes. Announcing a new data centre is considerably easier than establishing a competitive technology industry around it.
The energy requirements alone are substantial. The International Energy Agency estimated that data centres consumed around 485 terawatt-hours of electricity worldwide in 2025 and projected approximately 950 terawatt-hours by 2030 under its central scenario. Those figures include conventional computing and other data-centre activities, not AI alone, and the forecast is subject to uncertainty. Even so, they illustrate why the availability of electricity, grid connections and cooling infrastructure increasingly influences where new computing facilities can be built.
National strategies therefore need to consider more than acquiring processors. A successful AI industry requires people who can develop and maintain systems, businesses with practical uses for them and institutions capable of supporting research and investment. Countries that concentrate exclusively on the largest hardware projects may overlook less expensive ways of building useful technological capacity.
Africa’s Opportunity Begins With Access and Local Capability
Africa enters this changing landscape with considerable differences in infrastructure, investment and technical resources compared with established computing centres. Those differences are real, but they do not mean that meaningful participation requires African countries to recreate every part of the global AI industry.
The World Bank has estimated that average data-centre power capacity across Africa is far below the global level. Reliable electricity, connectivity and access to affordable computing remain constraints for many institutions and businesses. These limitations affect much more than AI; they influence digital commerce, research, public administration and the wider ability to use modern technology productively.
The African Union adopted a Continental Artificial Intelligence Strategy in 2024, recognising the importance of skills, infrastructure, responsible development and regional cooperation. Its value will depend on what countries and institutions build around those commitments rather than on the existence of a strategy alone.
A practical approach begins by asking what technologies people and businesses can use effectively. A Ugandan agricultural service may benefit from combining available AI tools with reliable local farming information. An educational application could help teachers prepare materials or support learners in languages and settings that larger international products have not adequately served. Health and public-service applications could also be useful when they are carefully tested and adapted to actual institutional conditions.
These projects require relevant information, professional oversight and technical competence, but they do not necessarily require a country to train an enormous general-purpose AI model from the beginning. Existing models, including appropriately licensed alternatives that can be adapted, may provide a more economical starting point.
In its World Development Report 2026, the World Bank described a progression from adopting existing AI tools to adapting them for local use and, where conditions permit, advancing domestic technological capabilities. This is not an argument for permanent dependence. It recognises that effective participation can develop through stages, and that building skills and useful services is itself a form of technological progress.
For Uganda, the supporting priorities remain familiar: affordable connectivity, reliable electricity, sound digital institutions and education capable of producing technically skilled people. The National Information Technology Authority’s strategic plan for 2025/26–2029/30 addresses broader digital infrastructure and electronic public services. Those foundations are relevant to AI even where the immediate investment is not specifically labelled an AI project.
There is also a regional opportunity in cooperation. Shared research resources, African-language datasets, technical education and compatible digital infrastructure could help institutions achieve more together than they might through isolated national efforts. Local businesses may eventually find that their strongest advantages lie in understanding customers and conditions that international developers know less well.
The question is not whether Africa can immediately match the largest AI industries in computing expenditure. It is whether African economies can become capable users, developers and suppliers of technologies that meet their own needs, while retaining access to competing international providers.
This returns us to the central lesson of the industrial revolutions. Technological power has always depended upon where productive resources are located, but the countries that benefit from a technology need not manufacture every component themselves. Electricity transformed economies far beyond the places where electrical equipment was invented. Computing became useful to businesses that never developed their own microprocessors, and the internet enabled enterprises in countries that did not build its earliest networks.
Artificial intelligence is likely to extend that pattern, although its benefits will not spread automatically. Countries able to combine access to computing with education, dependable infrastructure and practical applications will be better placed to participate. Those that neglect these foundations may remain purchasers of services whose price and availability are determined elsewhere.
The Fourth Industrial Revolution is therefore producing a geography of both competition and cooperation. Countries are trying to secure advantages in computing, research and industrial capacity, while relying on international networks that no single government can fully replace.
The challenge is not simply to determine which nation will possess the most powerful AI system. It is to understand how the technology’s benefits can be developed and shared across economies with very different resources and ambitions.
As earlier industrial revolutions demonstrated, the location of factories and infrastructure can shape economic influence for generations. In the age of artificial intelligence, that influence will also depend upon the ability to turn computing capacity into useful knowledge, services and industries.
The geography of technology is changing once again, but its future will be shaped as much by the connections countries maintain as by the capabilities they seek to control.
NEXT IN THE TREND REPORT
Computers Are Learning to Act
AI Agents Are Moving Beyond Conversation Into Performing Tasks
SELECTED SOURCES
Stanford University, The 2026 AI Index Report • European Commission, AI Factories • Government of India, IndiaAI Mission (2026) • International Energy Agency, Key Questions on Energy and AI (2026) • African Union, Continental Artificial Intelligence Strategy (2024) • World Bank, World Development Report 2026